Add-on interest is a flat-rate method where total interest is calculated up front on the full principal and added to the loan, which usually makes the loan costlier than a reducing-balance loan with the same quoted rate. Whether you are taking out a standard personal loan or a foreigner loan, lenders work out the interest once, add it to the amount borrowed, then split the total evenly across your repayment term. Below, we walk through how the maths works, what it means against an effective interest rate, and a checklist for comparing offers.
What Add-on Interest Actually Means
Add-on interest, sometimes called the flat-rate or pre-computed method, charges interest on the entire original loan amount for the whole term, even though you’re paying that amount down month by month. The lender multiplies the principal by the interest rate and by the loan term, then adds that figure to the principal before dividing everything into equal instalments.
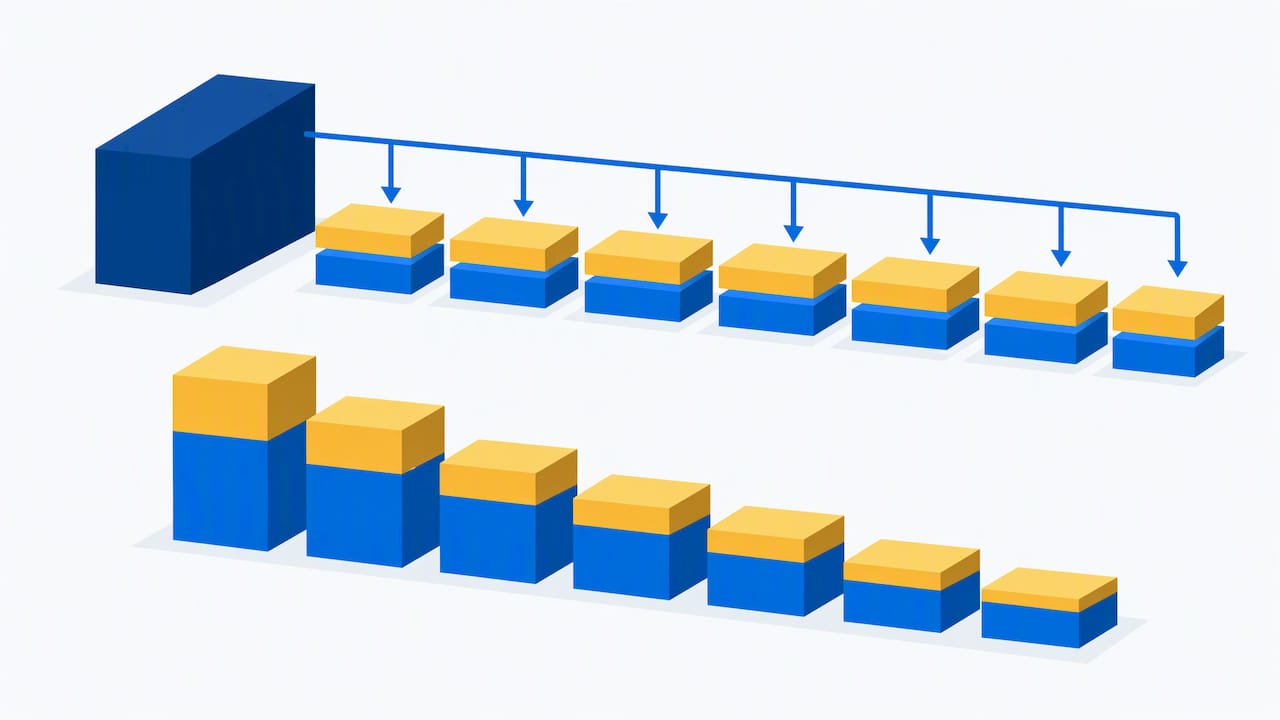
That’s the key difference from a reducing-balance loan, where interest is recalculated each month on whatever principal remains. With add-on interest, your monthly payment stays fixed not because the interest portion is shrinking, but because the total repayment, principal plus pre-calculated interest, is simply divided evenly across the term.
This method shows up most often in:
- Short-term instalment loans with fixed terms of one to five years
- Some fixed-deposit and add-on savings products
- Auto loans and certain personal instalment products where lenders prefer predictable, front-loaded returns
A Worked Example: Add-on Versus Reducing Balance
Numbers make the gap obvious.
- Add-on method: total interest is $10,000 × 8% × 2 years = $1,600. Total repayment becomes $11,600, split into 24 equal instalments of about $483 a month.
- Reducing-balance method: interest is recalculated monthly on the outstanding balance. At the same nominal 8% rate, total interest over the same term comes to roughly $868, bringing total repayment to about $10,868, or around $453 a month.
- The difference: the add-on loan costs close to $732 more in interest for an identical advertised rate and term, purely because of how the interest is calculated.
Why Effective Interest Rate Matters When Comparing Offers
The advertised add-on rate tells you almost nothing about what you’ll actually pay. The effective interest rate, or EIR, accounts for the declining balance and the timing of your repayments, which is why it’s consistently higher than the flat rate on the same loan.
Before signing anything, it’s worth doing the following:
- Ask the lender for both the advertised rate and the EIR, not just one
- Request a full repayment schedule showing principal, interest and balance for every instalment
- Compare total repayment amounts across offers, not just the headline percentage
- Check whether payment frequency changes the EIR, since more frequent instalments can push it higher even with identical principal and nominal rate
Tenure matters too: stretching the same loan over a longer period under the add-on method increases total interest proportionally, because the rate keeps applying to the original sum for longer.
Early Repayment, Rebates and the Fees That Catch Borrowers Out
Paying off an add-on loan early doesn’t automatically mean paying less interest. Because the interest was pre-computed on the full principal at the outset, whether you get a rebate, and how much, depends entirely on the rebate method written into your contract. Some agreements use an actuarial method, others a simple-interest approach, and some still reference the older Rule-of-78 calculation, each of which gives a different refund for the same early payoff.
Before signing, check for these contractual details:
- Processing or administration fees charged at disbursement
- Amendment fees if you change the repayment schedule later
- An early repayment or redemption charge, and how it’s calculated
- Late payment or default fees, and how quickly they accrue
Pro Tip: Ask your lender for a written early-settlement illustration showing the exact rebate amount you’d receive at several possible payoff dates, before you sign anything.
A Practical Checklist and What Transparency Should Look Like
A transparent lender makes these numbers easy to get, not something you have to chase down after signing. We structure our process around Singpass MyInfo for faster verification and we set out transparent fee structures so there are no hidden charges buried in the fine print.
When you’re evaluating any lender, add-on or otherwise, ask for:
- The effective interest rate alongside the advertised rate, in writing
- A complete repayment schedule covering every instalment to the final payment
- The exact early-settlement or rebate method named in the contract
- An itemised list of every fee that could apply, not just the headline interest
- A sample settlement figure showing what you’d owe if you repaid early at a specific date
Running the numbers yourself helps too. A loan calculator lets you model total repayments under different rate structures before you commit, which makes it much easier to see how an add-on quote stacks up against a reducing-balance alternative.
The Gap Between the Advertised Rate and the Real Cost
The single biggest misunderstanding borrowers carry into a loan agreement is assuming the advertised percentage is the whole story. It almost never is, and the add-on method is specifically where that assumption costs the most, because the rate you see is calculated on a principal that, in reality, you’re steadily paying down. Fixed monthly payments feel reassuring, but fixed doesn’t mean fair: it just means the lender has already decided how the total cost gets split across your term.
If there’s one habit worth building, it’s refusing to compare loans on advertised rate alone. Ask for the EIR, ask for the schedule, and treat any lender who hesitates on either as a signal to look elsewhere.
How We Handle Interest and Transparency at Magnus Credit
As a legally licensed money lender in Singapore, we set out rates and fees clearly from the start, so you’re comparing real numbers rather than guessing at what an advertised rate actually means once it’s applied to your loan. Our application process runs through Singpass MyInfo to speed up verification, and fee structures are presented upfront rather than being discovered partway through repayment.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Frequently Asked Questions
What does “add on interest” mean?
Add-on interest is a flat-rate method where a lender calculates total interest on the full original principal for the entire loan term, then adds that amount to the principal before dividing everything into equal instalments. Because the rate keeps applying to the original sum rather than a shrinking balance, it typically produces a higher total cost than a reducing-balance loan at the same advertised rate, as explained in Investopedia’s add-on interest guide.
How do you calculate add-on interest?
You multiply the principal by the annual interest rate and by the loan term in years to get total interest, then add that figure to the principal and divide by the number of instalments.
What is the difference between an effective interest rate and an add-on interest rate?
The add-on rate is applied to the full original principal for the whole term, while the effective interest rate (EIR) accounts for the declining balance and the timing of each repayment. MoneySense’s guidance confirms the EIR is consistently higher than the advertised flat rate and recommends asking lenders for both figures plus a full repayment schedule.
How much interest does $10,000 earn in a year?
This depends entirely on the interest rate and calculation method applied by the specific account or loan, so there’s no single figure that holds across products. The clearest way to find out is to ask for the exact rate, whether it’s flat or reducing-balance, and a written schedule showing the total interest for your specific term.